
Learn: First Citizens Bank Rewards
Everyday rewards from a trusted bank
Advertisements
Why It’s Worth It
No annual fee
Bonus everyday categories
Flexible point redemption
Intro balance transfer APR
About the First Citizens Bank Rewards Credit Card
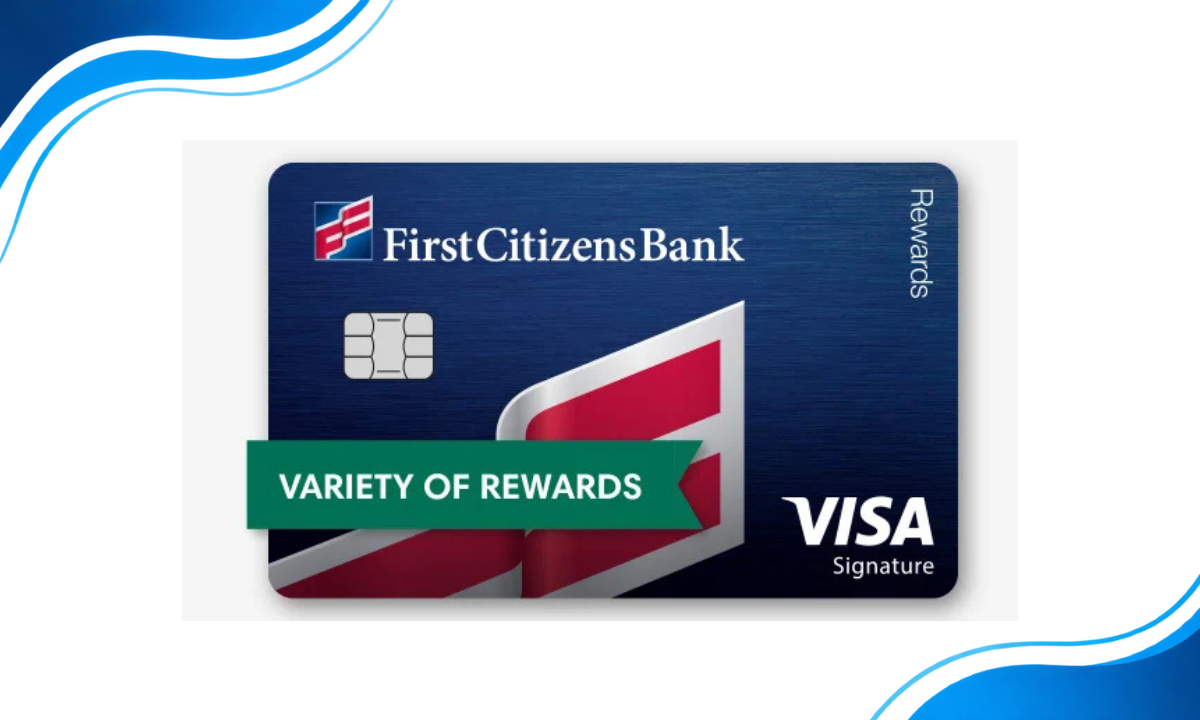
The First Citizens Bank Rewards Credit Card is positioned as an everyday rewards option for consumers in the United States who want straightforward value without paying an annual fee. Issued by First Citizens Bank, the card is not presented as a cobranded product tied to a retail or travel partner. Instead, it is built around the bank’s own rewards ecosystem, which may appeal to cardholders who prefer flexibility over brand-specific perks.
Its main attraction is the tiered rewards structure on routine spending categories. Cardholders earn 3 points per $1 on gas and select streaming services, 2 points per $1 on grocery and drugstore purchases, and 1 point per $1 on other qualifying purchases. For households that regularly spend in these categories, the card may offer more practical day-to-day value than flat-rate products. Points are posted daily, which can make the rewards experience feel more immediate.
The redemption side is also broad. Points may be used for cash back, deposits into eligible First Citizens checking or savings accounts, credits toward a First Citizens loan or mortgage, gift cards, merchandise, charitable donations, and the Pay Me Back® feature for qualifying purchases over $100 made within the required time frame. This flexible structure suggests the card is designed for users who want options rather than a single fixed reward path.
Additional value may come from the card’s 0% introductory APR on balance transfers for the first 12 billing cycles on transfers made within the first 90 days of account opening, after which a variable APR applies. The card also carries a $0 annual fee and may include added Visa benefits such as cell phone protection and roadside assistance, with enhanced Signature benefits available on qualifying credit lines.
For readers comparing everyday rewards cards, this product may stand out for combining bonus categories, redemption flexibility and no annual fee in one package. To see whether it matches your spending profile and to understand the next steps, it may be worth tapping below to learn how the application process works.
About First Citizens Bank
First Citizens Bank, formally known as First-Citizens Bank & Trust Company, is a long-established U.S. financial institution headquartered in Raleigh, North Carolina. Its history dates back to 1898, which places it among the more traditional banking brands in the American market. Rather than operating as a digital-only newcomer, First Citizens has built its reputation as a conventional full-service bank with a long-term approach, a broad branch presence, and a strong focus on relationship banking.
The institution is part of First Citizens BancShares, Inc. and offers a wide mix of services across personal and business finance. On the consumer side, its lineup includes checking accounts, savings products, mortgages, personal loans, credit cards and digital banking. Beyond that, it also serves small business, commercial and wealth management clients, which suggests a broader financial platform than a card issuer that only specializes in lending. For cardholders, that matters because the rewards ecosystem connects with other bank products, including eligible deposits into First Citizens checking or savings accounts and credits toward certain First Citizens loans or mortgages.
The bank is also notable for combining traditional banking infrastructure with modern account tools. Customers can manage accounts through online banking and the mobile experience, receive alerts, automate bill payments and access card controls such as temporary lock functions, lost or stolen card reporting and travel notifications. In practical terms, this makes the issuer feel like a legacy bank that has continued adapting to digital expectations rather than a branch-only institution.
From a trust perspective, First Citizens highlights its regulated status as a Member FDIC, and its brand positioning emphasizes stability, customer relationships and financial strength. That background may be reassuring for consumers who prefer a card from a longstanding banking group instead of a newer fintech platform.
Why choose the First Citizens Bank Rewards Credit Card?
The First Citizens Bank Rewards Credit Card appears best suited to consumers who want an everyday rewards card with no annual fee and who spend regularly on routine household categories. Its rewards structure is particularly relevant for people who frequently buy gas, groceries, drugstore items and select streaming services. Earning 3 points per $1 on gas and select streaming, 2 points per $1 on grocery and drugstore purchases, and 1 point per $1 on other qualifying purchases gives it a practical profile for ordinary monthly spending rather than luxury-only use.
This card may also suit people who value redemption flexibility. Points can be used for several options, including:
- Cash back as a statement credit
- Deposit into an eligible First Citizens checking or savings account
- Gift cards and merchandise
- Credits toward a First Citizens personal loan or mortgage
- Pay Me Back® redemptions for eligible purchases over $100 made within the required time frame
- Donations to Teen Cancer America
Another point in its favor is the introductory financing feature. For applicants planning to consolidate existing card balances, the product includes a 0% introductory APR for the first 12 billing cycles on balance transfers made within the first 90 days of account opening, although a balance transfer fee applies. This makes the card potentially interesting not only for rewards seekers but also for those looking to reorganize debt at a lower temporary cost.
In profile terms, this is not presented as a card for damaged credit, nor as an ultra-premium travel card aimed at very high-income households. It sits more naturally in the mainstream rewards category: suitable for consumers with solid credit who want useful bonus categories, ongoing Visa benefits, digital account controls and the familiarity of a traditional bank. For readers looking for a practical card that combines everyday earning, flexible redemption and a recognized banking issuer, this option may deserve a closer look before applying.