How to apply for your First Citizens Bank Rewards Card
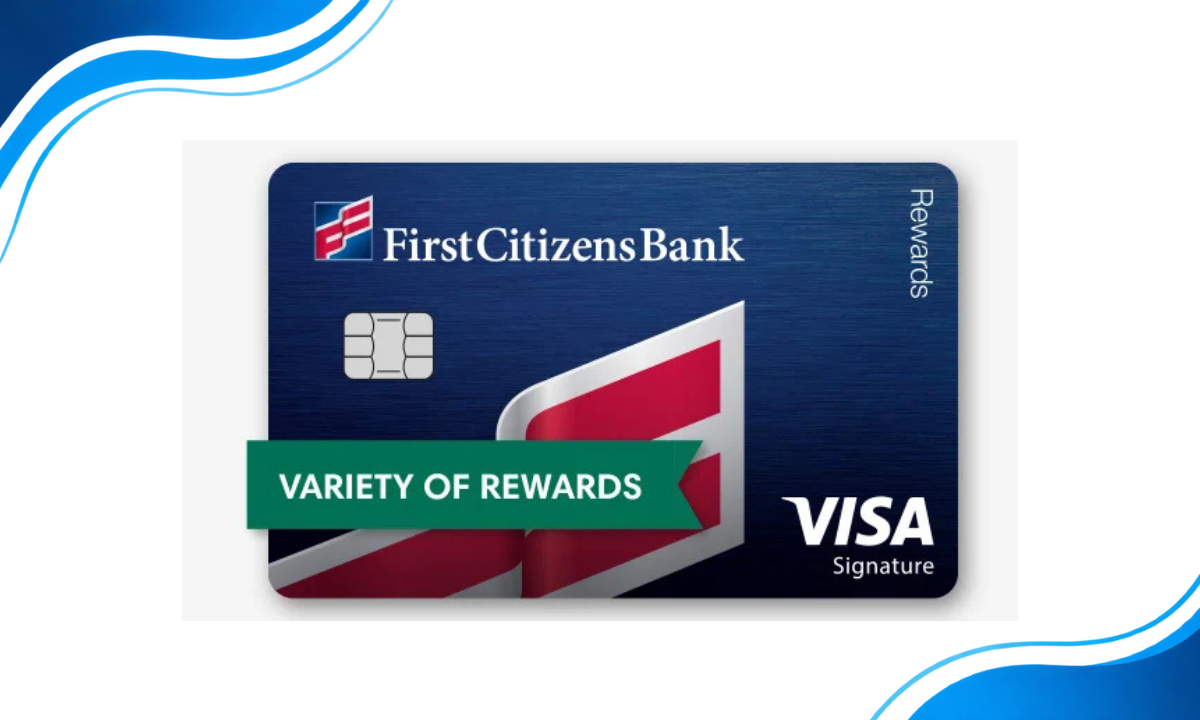
The First Citizens Bank Rewards Card is designed for consumers in the United States who want a practical rewards credit card tied to routine household spending rather than luxury travel alone. Issued by First Citizens Bank, this card combines category-based points earning, a $0 annual fee, and redemption flexibility that may appeal to cardholders looking for steady value from groceries, gas, drugstores and select streaming services. It is also positioned as a mainstream rewards option, which makes it relevant for people comparing everyday-use credit cards instead of premium products with high annual costs.
Another notable element is its balance transfer feature. Eligible applicants may receive a 0% introductory APR for the first 12 billing cycles on balance transfers made within the first 90 days, after which a variable APR applies based on creditworthiness. Combined with digital account management, contactless payments and Visa-related protections, the card sits in a category that rewards regular spending while still offering some practical financial tools for cardholders who want to consolidate debt or simplify account management.
First Citizens Bank Rewards Card: Earn Points on Everyday Spending
The main strength of the First Citizens Bank Rewards Card is that it rewards purchases many households already make each month. Cardholders earn 3 points per $1 on gas and select streaming services, 2 points per $1 on grocery and drugstore purchases, and 1 point per $1 on other qualifying purchases. That structure may work especially well for commuters, families and users who want their card to support ordinary expenses rather than occasional travel bookings.
The card also stands out for the way points can be used. Rewards may be redeemed for cash back, deposits into eligible First Citizens checking or savings accounts, credits toward a First Citizens personal loan or mortgage, gift cards, merchandise, and Pay Me Back® redemptions on qualifying purchases over $100 made within the required time frame. In addition, points post daily, which can make account activity easier to track. There is also no annual fee, and customers with a credit line of $5,000 or more may be automatically enrolled in additional Visa Signature benefits, subject to terms and exclusions.
Detailed Card Benefits
- Bonus categories for everyday purchases: 3 points on gas and select streaming, 2 points on groceries and drugstores, 1 point on other qualifying purchases.
- Daily points posting: rewards are added to the account daily instead of on a monthly cycle.
- No annual fee: the ongoing cost of simply keeping the card is $0.
- Introductory balance transfer offer: 0% intro APR for 12 billing cycles on qualifying transfers made within 90 days of account opening.
- Flexible rewards program: redemptions include statement credit, bank deposit, gift cards, merchandise, loan or mortgage credits, charitable donations and Pay Me Back®.
- Card management tools: temporary lock, lost or stolen card reporting, travel notices, text and email alerts, bill payment tools and digital banking access.
- Visa protections: depending on account type and credit line, benefits may include cell phone protection, roadside assistance and other Visa coverage subject to program terms.
- Contactless payment: supports tap-to-pay transactions for convenience and security.
Initial Credit Limit
First Citizens does not publish a universal starting credit limit for the Rewards Card. The initial credit limit is determined after approval and depends on the applicant’s creditworthiness, income, existing debt obligations and internal underwriting criteria. The bank states that the credit limit will be disclosed when the card is delivered and will also appear on billing statements.
A practical clue appears in the benefits structure: applicants who receive a credit line of $5,000 or more may qualify for additional Visa Signature benefits. This does not mean every approved applicant will receive that amount, only that benefit eligibility may expand at that threshold.
Requirements
As with most unsecured rewards credit cards, the First Citizens Bank Rewards Card is generally intended for applicants with solid credit profiles, although the bank does not publish a minimum score requirement. Normal credit approval applies, and approval may depend on factors such as credit history, income, debt-to-income ratio, employment details and overall financial profile.
Applicants should expect to provide standard personal information, including full legal name, residential address, Social Security number, date of birth, income information and employment details. Existing First Citizens Digital Banking customers can begin the application by signing in and verifying their personal information. New customers may first need to establish a relationship with the bank through an eligible checking account if they want to use the bank’s guided online application path. Applicants must also be legal U.S. residents of eligible age and able to meet identity verification requirements.
About the Bank
First Citizens Bank, formally First-Citizens Bank & Trust Company, is one of the longest-standing banking institutions in the United States. Its history dates back to 1898, giving it well over a century of operating experience. Headquartered in Raleigh, North Carolina, the institution has built its reputation around relationship banking, a broad product lineup and long-term financial stability rather than a fintech-style, app-only model.
The bank is part of First Citizens BancShares, Inc. and offers a full suite of financial services, including checking accounts, savings products, mortgages, personal loans, business banking, commercial banking and wealth management. This matters for Rewards Card holders because the card’s ecosystem is linked to broader bank services, especially when points are redeemed into eligible deposit accounts or used toward certain First Citizens loans or mortgages. The bank also emphasizes digital banking tools, account alerts, mobile access and card controls. From a trust perspective, it identifies itself as Member FDIC, and its longstanding presence may reassure consumers who prefer an established issuer.
Who Is This Card For?
The First Citizens Bank Rewards Card is best suited to people who spend consistently on ordinary categories such as gas, groceries, drugstores and select streaming services. That makes it relevant for commuters, families, suburban households and users who want a card that can generate points from recurring monthly needs rather than specialized luxury spending. It may also appeal to people who dislike annual fees but still want access to a structured points program.
The card may also fit applicants who value redemption flexibility more than brand-specific travel perks. Since points can be applied to cash back, deposits, statement credits, eligible loan balances, gift cards and merchandise, it offers several ways to extract value. In addition, someone planning a balance transfer may find the introductory 0% APR offer useful. On the other hand, this is probably not the strongest fit for consumers seeking premium airport travel benefits, fixed-value flat-rate rewards across all purchases, or a card targeted specifically to rebuilding credit.
How the First Citizens Rewards Program Works
The First Citizens Rewards Program is centered on category-based points accumulation. For each net dollar spent, cardholders earn points according to the merchant category: 3 points on fuel and select streaming services, 2 points on grocery and drugstore purchases, and 1 point on all other qualifying purchases. Points are calculated on actual spending and may be rounded up or down to the nearest point. Returned purchases reduce the rewards balance accordingly.
The program includes a cap of 10,000 points per calendar month, which is an important detail for higher-spending households. Points remain eligible for redemption for 3 years from the original month earned, after which they expire. Redemption options are broad and include:
- Cash back as a statement credit
- Deposit into an eligible First Citizens checking or savings account
- Credits toward a First Citizens personal loan or mortgage
- Pay Me Back® for qualifying purchases over $100 made within 60 days
- Gift cards
- Merchandise
- Donations to Teen Cancer America
For rewards access, customers can log in through Digital Banking and select Rewards Balance, or visit the dedicated rewards platform at default. The First Citizens Rewards Call Center is listed at 866-645-1694 for certain redemption assistance.
Step-by-Step Guide to Apply
Applying for the First Citizens Bank Rewards Card is most straightforward for existing customers enrolled in Digital Banking, but the bank also provides a path for new customers. A careful application process may improve the experience:
- Review the card details and pricing information on the official page: credit card.
- Check the pricing disclosure before applying: rewards pricing.
- If already a First Citizens Digital Banking customer, sign in at https://app.firstcitizens.com/sign-in/?product=LN47R.
- Verify personal information, including name and address.
- Confirm the product selection to ensure the Rewards Card is the chosen application.
- Enter income, employment and other required financial details.
- Submit the application and wait for the bank’s credit review and decision.
- If not yet a customer, review checking account options here: compare, since the bank’s application flow references existing banking relationships for digital applications.
For account management after approval, the mobile app is available on Android at googlel and on iPhone at apple.
Pros and Cons of the Card
From a practical perspective, the First Citizens Bank Rewards Card offers an appealing mix of value and simplicity. Its strongest positives are the $0 annual fee, the category bonuses tied to everyday spending, and the broad redemption menu. Consumers who regularly buy gas, groceries and pharmacy items could generate better value than with some basic flat-rate cards, especially if they also use streaming services that qualify. The balance transfer offer may add further utility for applicants looking to consolidate existing card debt at a temporary promotional rate.
Still, there are limitations worth weighing. First, the card has a 10,000-point monthly earning cap, which may reduce its usefulness for heavy spenders. Second, the points program is flexible, but exact point values can vary by redemption type, meaning consumers should review examples before assuming equal value across all uses. Third, foreign purchases incur a 3% foreign transaction fee, making the card less attractive for international use. In addition, while the balance transfer offer is valuable, it comes with a fee and only applies to transfers made within the first 90 days. Finally, the published APR range can be relatively high for applicants who do not pay balances in full.
How to Activate the Card?
Once approved, the cardholder typically receives the physical card by mail along with activation instructions. The activation process is usually completed by following the instructions included with the card package or by using the bank’s digital banking channels if activation is enabled there. After activation, it is advisable to create or confirm Digital Banking access, review the assigned credit limit, set up alerts and enroll in automatic payments if desired.
To manage the card after activation, cardholders can use First Citizens Digital Banking and the mobile banking app. These tools also support security actions such as temporary card lock, reporting a lost or stolen card and adding travel notices.
Fees and Charges
The First Citizens Bank Rewards Card carries no annual fee, which is a major advantage for long-term holding. The purchase APR ranges from 16.49% to 25.49% variable, based on creditworthiness. The cash advance APR ranges from 25.49% to 28.49% variable. Balance transfers made within the first 90 days of account opening may receive a 0% introductory APR for 12 billing cycles; after that, the variable APR becomes 16.49% to 25.49%.
- Annual fee: $0
- Balance transfer fee: either $5 or 3% of each transfer, whichever is greater
- Cash advance fee: either $10 or 5% of each advance, whichever is greater
- Foreign transaction fee: 3% of each transaction in U.S. dollars
- Late payment fee: up to $39
- Returned payment fee: up to $25
- Minimum interest charge: $1
Customer Service
For official assistance regarding the First Citizens Bank Rewards Card, readers can use the following channels:
- Official card page
- General support center
- Call First Citizens Bank: 1-800-543-9000
- Rewards Call Center: 866-645-1694
- Digital Banking login
- Secure messages for account questions
- Locations finder
- Privacy and security
- Other contact support
For applicants researching the card before submitting a request, reviewing both the official product page and the pricing disclosure is a prudent step. That approach helps clarify whether the First Citizens Credit Card Rewards structure aligns with personal spending habits and borrowing needs.
About the author

Alex is a content writer focused on credit cards, personal loans, and everyday financial decisions. He enjoys turning complex financial topics into clear, practical information that helps readers understand their options and make informed choices.