How to apply for your Klarna Credit Card
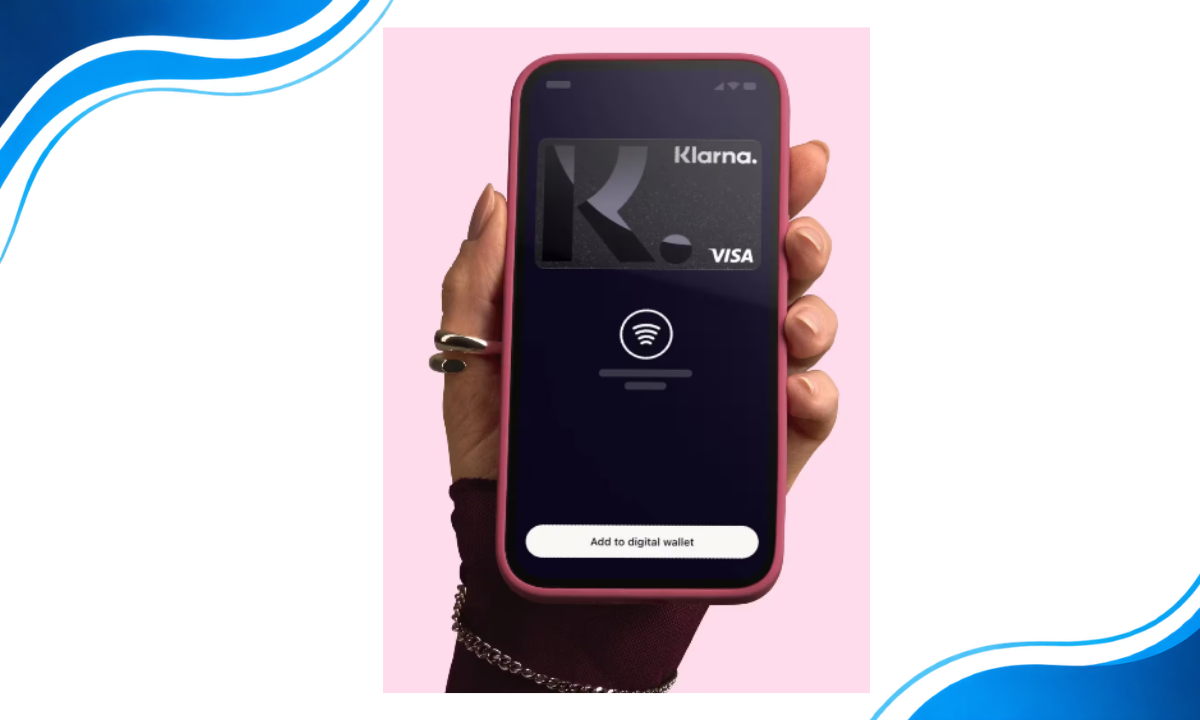
The Klarna Credit Card is designed for consumers in the United States who want a more flexible alternative to a traditional credit card. Issued by WebBank pursuant to a license from Visa U.S.A. Inc., it combines the broad acceptance of the Visa network with Klarna’s app-based payment tools. In practice, this means cardholders can use it online and in stores where Visa is accepted while managing purchases inside the Klarna ecosystem.
What makes the product stand out is its emphasis on payment choice rather than classic points or airline miles. Eligible purchases can potentially be paid in full, deferred to the end of the month, moved to the next month, split through Klarna’s Pay in 4 structure, or financed over a longer term. For users already familiar with Klarna, the card extends that same flexible-payment logic to a wider range of everyday spending.
Klarna Credit Card: Flexible Payments for Modern U.S. Shoppers
The main appeal of the Klarna Credit Card is flexibility. Instead of assigning every transaction to the same repayment model, Klarna allows users to decide how eligible purchases should be handled after they are made. This can be especially useful for shoppers managing uneven monthly cash flow or those who want short-term installment options without applying for a separate financing product each time.
Other notable benefits include no monthly fee, no annual fee, and no foreign transaction fees according to Klarna’s official product page. The card also supports Apple Pay and Google Pay, and applicants can receive a virtual card quickly after approval. In addition, Klarna states that applying involves a soft credit check, so there is no credit impact to apply. These features make the card particularly attractive to digital-first users who prioritize convenience, app control, and clear repayment options over premium lounge access or travel rewards.
Detailed Card Benefits
- Visa acceptance: usable anywhere Visa is accepted in the U.S. and internationally.
- Flexible repayment choices: Pay in 4 for eligible purchases of $30 or more, pay in full, pay later at month-end, move a purchase forward, or split purchases over 3 to 18 months.
- No annual fee: helpful for cost-conscious cardholders who do not want to pay simply to keep the card open.
- No monthly fee: reduces recurring ownership costs.
- No foreign transaction fees: potentially useful for international travel or online cross-border shopping.
- Digital wallet compatibility: supports Apple Pay and Google Pay.
- Fast digital issuance: approved users may access a virtual card in the app within minutes.
- Integrated app management: repayment choices, purchase tracking, and account actions are centralized in the Klarna app.
Requirements
Eligibility for the Klarna Credit Card is more specific than for some entry-level credit cards. Based on Klarna’s official information, an applicant must be at least 18 years old, reside in the United States, and have used Klarna before and paid on time at least once. Klarna also states that applicants must pass a credit assessment based on a soft credit check.
The product is available in the 50 U.S. states and Washington, D.C., but it is not available in Puerto Rico, the U.S. Virgin Islands, or other U.S. territories. Klarna also notes that applications are currently unavailable in Wisconsin. As with most financial products, applicants should be prepared to provide personal identification details, contact information, and other data required for eligibility and identity verification.
About the Financial Institution
Klarna is a financial technology company founded in Sweden in 2005. Over the past two decades, it has grown into one of the best-known names in the global buy now, pay later market. Rather than operating like a traditional U.S. retail bank with branches and a broad deposit-and-lending model, Klarna is primarily known for digital checkout solutions, app-based shopping tools, and payment flexibility.
In the United States, Klarna’s brand has been built around installment payments, shopping discovery, order tracking, and app-managed financial features. The Klarna Credit Card reflects that identity: it is not marketed mainly as a premium rewards card, but as a modern payment tool integrated with an app-led shopping experience. It is important to note that the U.S. credit card is issued by WebBank, while Klarna provides the technology platform, user experience, and repayment functionality. Klarna Inc. is also associated with products such as Klarna balance and cashback-related features inside the app, although cashback availability may depend on separate eligibility and terms.
Who Is This Card For?
The Klarna Credit Card is best suited to consumers who already understand and appreciate Klarna’s repayment style. Existing Klarna users are the clearest target audience, especially those who have already completed purchases through Klarna and paid on time. The product may also fit younger and middle-aged adults who prefer handling finances through a smartphone rather than through branch visits or paper-heavy processes.
It may be a good fit for shoppers who value payment flexibility more than traditional rewards. Those who want to choose between paying in full, paying later, or splitting select purchases into installments may find this structure more useful than a standard flat-rate card. On the other hand, consumers focused on luxury travel perks, rich points programs, airport lounge access, or balance transfer promotions may find the card less aligned with their goals.
Detailed Program and Rewards
The Klarna Credit Card does not appear to center its value proposition on a conventional rewards framework such as unlimited cashback on every purchase, airline miles, or tiered points categories. Instead, its standout “program” is its repayment flexibility. Cardholders can decide how eligible purchases are handled after the transaction posts, which is a different proposition from standard rewards cards.
That said, Klarna’s broader ecosystem includes cashback deals in the Klarna app, subject to separate terms. According to Klarna’s published terms, cashback is tied to eligible purchases made through participating stores and is generally credited to a Klarna balance account. Users typically need both the Klarna app and an active Klarna balance to receive cashback, and payout timing can vary from several weeks to several months depending on the merchant and approval process. Because these cashback deals are separate from the core credit card structure, consumers should view them as an additional ecosystem benefit rather than a guaranteed card reward on every purchase.
For many users, the practical “reward” is the ability to spread costs strategically. Pay in 4 can be activated for eligible purchases of $30 or more within 12 hours of the transaction, with 25% due immediately and the remaining payments due every two weeks over six weeks. Klarna also discloses that a 28.99% APR applies to moved or split transactions, so longer financing options should be used carefully.
Initial Credit Limit
Klarna does not publicly advertise a standard initial credit limit for every approved applicant. In practice, the starting limit is likely individualized based on factors such as the applicant’s credit profile, previous Klarna usage, repayment history, and internal eligibility review. Because the application uses a soft credit check, the initial approval stage may feel less intrusive than a traditional hard-pull application, but that does not guarantee a high limit.
Applicants considering the card should treat the assigned limit as a variable rather than a published benefit. Consumers seeking a card primarily for a large upfront line of credit may prefer to verify current terms directly with Klarna before applying.
Step-by-Step Guide to Apply
Applying for the Klarna Credit Card is positioned as a quick digital process. Klarna also allows applications through its mobile app, which is central to the overall experience.
- Download the Klarna app if it is not already installed. Android or iOS.
- Sign in or create a Klarna account. Existing Klarna use is part of the eligibility criteria.
- Locate the credit card application section in the app or use the official card page online.
- Submit the requested information, including identity and contact details.
- Complete the eligibility review. Klarna states that the application uses a soft credit check, so there is no credit impact to apply.
- Receive a decision. If approved, a virtual card may become available in minutes.
- Add the card to Apple Pay or Google Pay to begin using it online or in stores where Visa is accepted.
- Order a physical card in the app if desired for broader in-person usability.
If an application is declined, Klarna indicates that eligibility can change over time, so reapplying in the future may be possible.
Pros and Cons of the Card
Pros: The Klarna Credit Card stands out for repayment flexibility, which is still unusual in the broader U.S. credit card market. Users can manage purchases individually rather than placing all spending under one repayment structure. The absence of annual fees, monthly fees, and foreign transaction fees is another strong advantage. The application process is digital, fast, and based on a soft credit check, which lowers the barrier for consumers who are comparison shopping. Visa acceptance and digital wallet compatibility also improve usability.
Cons: The card is not ideal for everyone. It appears less compelling for consumers seeking traditional points, miles, sign-up bonuses, or premium travel protections. Eligibility is narrower than some mainstream credit cards because applicants must have used Klarna previously and paid on time at least once. Another important drawback is cost on financed balances: Klarna discloses that 28.99% APR applies to moved or split transactions. That means longer repayment choices, while flexible, can become expensive if overused. In addition, cash withdrawals from ATMs are not allowed, and published information does not clearly disclose minimum or maximum credit limits.
How to Activate the Card?
Activation is closely tied to the Klarna app. After approval, Klarna states that the virtual card becomes active and ready to use right away. Users can typically access it in the app, then add it to Apple Pay or Google Pay for immediate online or in-store purchases. If a physical card is ordered, activation instructions should appear in the app once it arrives.
To reduce issues, it is advisable to verify personal information, enable app notifications, and review the repayment options for each purchase before use. Since the card experience is strongly app-centered, keeping the app updated is also important for smooth activation and account management.
Fees and Charges
The Klarna Credit Card’s official page highlights a relatively simple fee structure. Klarna states there are no monthly fees, no annual fees, and no foreign transaction fees. This makes the card potentially attractive for users who want to avoid recurring ownership costs or extra charges on international spending.
However, “no fee” does not mean “no cost” in every scenario. Klarna’s disclosures indicate that 28.99% APR applies to moved or split transactions. That is a key point, because the card’s main value lies in flexible repayment, and some of those options may trigger interest. Consumers should also remember that cashback-related benefits in the Klarna ecosystem have separate terms and are not the same as automatic rewards on all card purchases. Before applying, it is sensible to review the latest legal and pricing information at legal and the card page itself.
Customer Service
For support related to the Klarna Credit Card, users can rely on Klarna’s official service channels. Main references include the official card page at credit card and the customer support portal at customer service/. Klarna also provides in-app support options and help articles through its mobile platform.
For Klarna balance-related questions, published terms reference the phone number 1-888-518-2771. The company address listed in Klarna’s terms is Klarna Inc., 800 N. High St., Columbus, OH 43215. Additional legal information can be reviewed at legal. Because product terms may change, checking the app or the official website before making a financial decision remains advisable.
About the author

Alex is a content writer focused on credit cards, personal loans, and everyday financial decisions. He enjoys turning complex financial topics into clear, practical information that helps readers understand their options and make informed choices.