How to apply for your Affirm Card
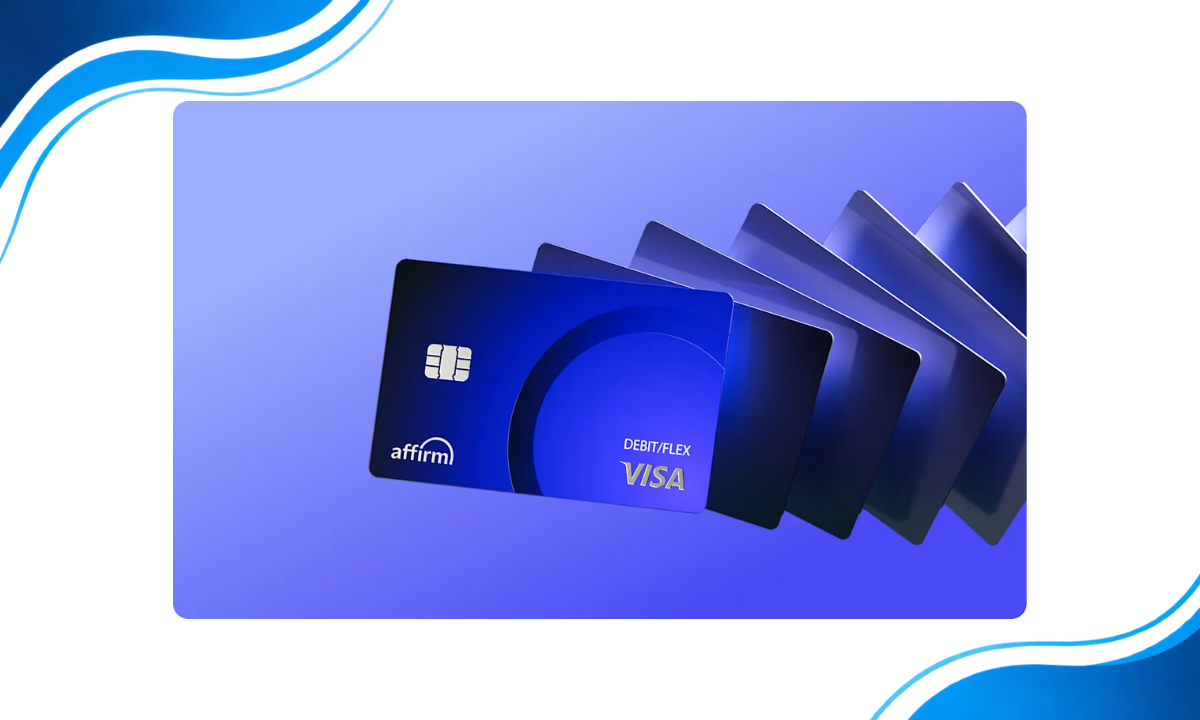
The Affirm Card is an everyday payment product designed for consumers in the United States who want more control over how and when purchases are paid. Although many people search for an “Affirm credit card,” the product is officially structured differently: it is a Visa debit card issued by Evolve Bank & Trust or Stride Bank, N.A., Members FDIC, and paired with Affirm’s buy now, pay later technology. This means a cardholder may pay in full for routine spending or request to split eligible purchases into installments through the Affirm app.
Its main appeal lies in transparency. Affirm promotes no annual card fee, no late fees, and no hidden fees, while eligible plans may include Pay in 4 at 0% APR or longer monthly installments with disclosed rates from 0% to 36% APR, based on credit and eligibility. In practice, the Affirm Card may suit budget-focused users who prefer fixed payment terms over revolving balances and want a product that works anywhere Visa is accepted in the United States.
Affirm Card: Flexible Payments for Everyday Purchases
The main benefit of the Affirm Card USA is flexibility. Instead of committing every purchase to a revolving credit balance, the user can decide whether to pay immediately or request a structured installment plan for eligible transactions. This design may be appealing to people who prefer to organize spending purchase by purchase rather than manage a single large balance.
Another notable advantage is cost clarity. Affirm states that the card has no card fees, no hidden fees, and no late fees. For approved plans, the repayment amount is shown in advance, which may help consumers understand the full cost before confirming the transaction. The product also benefits from broad usability because it can be used anywhere Visa is accepted, online and in stores, while the app provides centralized control over payments, plan requests, and purchase tracking.
Detailed benefits and features
- Flexible payment choice: pay in full for everyday purchases or request to pay over time through the Affirm app.
- Wide merchant acceptance: usable anywhere Visa is accepted, which makes it more versatile than many merchant-specific installment tools.
- Transparent repayment terms: eligible monthly plans display rates upfront, with no deferred-interest structure.
- Pay in 4 option: some eligible purchases may qualify for four interest-free payments at 0% APR.
- Longer installment plans: depending on the purchase and eligibility, monthly plans may extend beyond four payments.
- No annual fee: official materials highlight that the card itself does not charge standard card fees.
- No late fees: unlike some traditional lending products, Affirm says it does not charge late fees.
- App-based management: users can monitor purchasing power, track purchases, request plans, and manage payments from the mobile app.
- Debit-style foundation: linking a bank account supports pay-in-full functionality and everyday spending utility.
- Up to 24 hours to split eligible purchases: official content indicates some eligible purchases may be converted into a payment plan after the transaction.
Requirements
Applicants generally need to meet basic eligibility standards in the United States. The card is intended for U.S. consumers and is not available to residents of U.S. territories. As with most financial products, the applicant should be at least 18 years old, provide accurate personal information, and complete identity verification steps requested during sign-up.
Because installment options depend on approval, an eligibility check may be performed when a user requests a payment plan. Rates can range from 0% to 36% APR, depending on credit and other underwriting considerations. A down payment may also be required for some purchases. In addition, users who want the full debit-style experience may need to link a bank account in the app, as this supports paying in full and may unlock the best everyday-use features of the card.
About the Financial Institution
Affirm, Inc. is a U.S. financial technology company founded in 2012 by Max Levchin, one of PayPal’s co-founders. Since entering the market, the company has focused on installment-based consumer finance with an emphasis on transparency, fixed payments, and digital convenience. Rather than operating like a traditional bank, Affirm functions as a fintech platform that connects consumers, merchants, and bank partners.
This distinction is important for anyone researching the Affirm Card review. Affirm itself is not a bank. The Affirm Card is issued by Evolve Bank & Trust or Stride Bank, N.A., Members FDIC, pursuant to Visa licenses. Other products in the ecosystem, such as certain one-time-use virtual cards, may be issued by Cross River Bank, Sutton Bank, or Celtic Bank. Over the years, Affirm has built a strong digital presence through its mobile-first experience, merchant partnerships, and buy now, pay later model that aims to show consumers the total cost before they commit.
Who Is This Card For?
The Affirm Card may be most appropriate for consumers who value structured budgeting more than traditional rewards. A person who prefers to see the cost of each purchase clearly, decide in advance how to repay it, and avoid open-ended revolving balances may find the product especially relevant. It may also suit users who are comfortable managing money through a mobile app and appreciate being able to review purchasing power before shopping.
On the other hand, this product may be less suitable for people whose main priority is premium card perks such as airline miles, airport lounge access, luxury hotel status, or elevated cashback categories. The card is better understood as a flexible payments tool than a classic rewards credit card. In that sense, the ideal customer profile is a practical spender seeking payment flexibility, broad acceptance, and predictable terms rather than travel or lifestyle benefits.
Detailed program and rewards
The Affirm Card does not appear to operate as a traditional rewards card. There is no standard points, miles, or cashback structure prominently featured in the official product information. Instead, the product’s central “program” is its flexible payment framework. Eligible purchases may receive different financing options depending on transaction size, merchant participation, and the customer’s eligibility profile.
These options can include:
- Pay in full: useful for daily purchases when the cardholder wants a straightforward debit-style transaction.
- Pay in 4: four interest-free payments every two weeks on eligible purchases, at 0% APR.
- Monthly installment plans: plans such as 3, 6, 12 months, and in some cases longer terms, with fixed payments and disclosed APR.
From a practical standpoint, the value proposition is not based on earning rewards after spending, but on managing cash flow more predictably while shopping. For many consumers, that can be more useful than a modest cashback rate, especially when trying to avoid carrying a large revolving balance on a traditional credit card.
Step-by-Step Guide to Apply
For readers searching Apply for Affirm Card or Affirm Card application, the request process is primarily digital and app-based.
- Visit the official product page: open card and review the current disclosures, eligibility notes, and terms.
- Create or access an Affirm account: sign up with your personal details or log in if you already use Affirm.
- Download the mobile app: Android /iPhone
- Go to the Card section in the app: official instructions indicate users should open the app and tap Card.
- Review your purchasing power: the app may show an estimate of how much you can spend over time.
- Request the card and set up usage features: follow on-screen identity verification and account setup steps.
- Link your bank account: this step may be important for activating pay-in-full functionality and accessing the best features.
- Start using the card: once approved and set up, use it online or in person wherever Visa is accepted.
Because product terms can change, it is advisable to confirm all current details directly on the official Affirm page and in the app before proceeding.
Pros and Cons of the Card
From a consumer-finance perspective, the Affirm Card benefits are strongest in budgeting, flexibility, and transparency. The ability to pay in full or split eligible purchases into structured installments may be useful for people who want tighter control over monthly cash flow. The lack of annual fees, hidden fees, and late fees is another positive, especially in comparison with some traditional cards that combine annual fees, penalty fees, and complex interest structures.
Still, there are limitations that deserve attention. First, this is not a classic rewards card, so users looking for cashback or travel benefits may be disappointed. Second, although some plans are interest-free, longer monthly plans can carry APR from 0% to 36%, which may become expensive depending on the consumer’s profile and purchase size. Third, approval and available options vary by purchase and eligibility, so flexibility is not guaranteed on every transaction. Finally, people expecting a standard credit line and traditional credit-card statement cycle may need time to adapt to the product’s app-centered, installment-oriented model.
- Pros: flexible payment choices, no annual fee, no late fees, transparent terms, wide Visa acceptance, app-based control.
- Cons: limited traditional rewards, potential interest charges on monthly plans, variable eligibility, less suitable for those seeking premium perks or a classic credit line.
How to Activate the Card?
Activation is typically handled through the Affirm app, which is central to the entire card experience. After approval and receipt of the card, the user should log in to the app, navigate to the card management area, and follow the prompts to confirm the card details and enable usage. If required, the user may also need to verify identity and link a bank account before accessing all features.
Officially, Affirm encourages users to open the app, tap Card, and use that section to review purchasing power, request plans, and track spending. The activation flow may vary slightly over time, so the most reliable approach is to complete the process using the current instructions available in the official mobile application.
Fees and Charges
One of the strongest points in the official positioning of the Affirm Card fees explained is simplicity. Affirm states there are no card fees, no hidden fees, and no late fees. That means no annual fee is highlighted for the card itself, and no penalty late fee is charged if a scheduled installment payment is missed.
However, “no fees” should not be confused with “always free financing.” Eligible monthly plans may carry 0% to 36% APR, based on credit and eligibility. Some transactions may also require a down payment. Since options vary by merchant and purchase amount, the real cost depends on the specific plan presented in the app. Readers should also review the terms page at terms and the lender disclosures at lenders before accepting any financing offer.
Customer Service
Consumers who need support for the Affirm Card login, payments, eligibility, or general account questions can use Affirm’s official service channels. The primary website for the product is card, while the main Help Center is available at help center and help. General company information can be found at about. If telephone or live chat availability changes, the most reliable source for updated contact options is the official Help Center and the logged-in app environment, where account-specific assistance is typically offered.
About the author

Alex is a content writer focused on credit cards, personal loans, and everyday financial decisions. He enjoys turning complex financial topics into clear, practical information that helps readers understand their options and make informed choices.