
Learn: Truist Enjoy Cash
Flexible cash back with Truist relationship perks
Advertisements
Why It’s Worth It
No annual fee
Flexible cash back
0% intro APR
Loyalty bonus boost
About the Truist Enjoy Cash Card
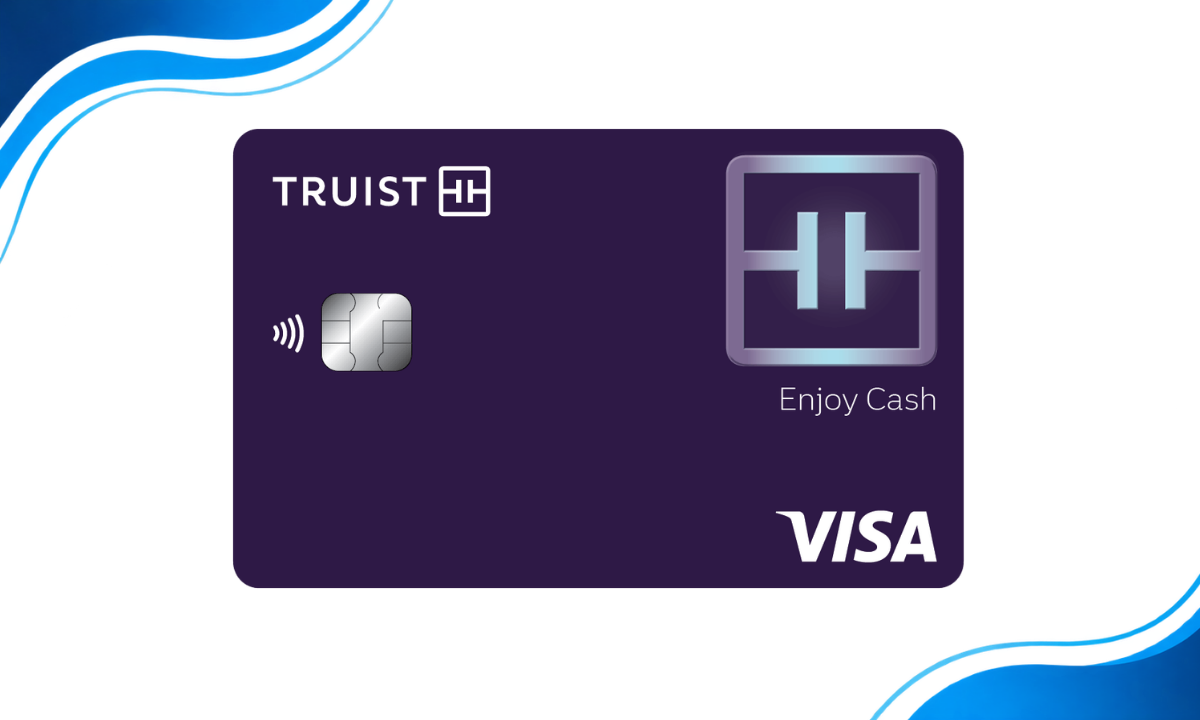
The Truist Enjoy Cash Card is positioned as a no-annual-fee cash back credit card for consumers in the United States who prefer flexible rewards and straightforward everyday value. Issued by Truist, the card is not presented as a cobranded product; instead, it sits within Truist’s broader lineup of consumer credit cards and focuses on practical spending categories, introductory financing, and digital account tools.
One of the card’s most notable features is that applicants may choose between two rewards structures at the time of application. One option offers 3% cash back on gas and EV charging, 2% on groceries and utilities, and 1% on all other eligible purchases, with a combined $1,000 monthly spending cap on the 2% and 3% categories. The second option offers a simpler 1.5% cash back on all eligible purchases. Truist indicates that this selection cannot be changed later, which makes the decision at application especially important.
Beyond rewards, the card includes a 0% introductory APR for 12 months on purchases and a 0% introductory APR for 12 months on balance transfers made within the first 90 days after account opening. After that period, a variable APR applies based on creditworthiness. For individuals looking to finance a large purchase or consolidate existing balances, this introductory structure may stand out as a useful feature, particularly when paired with the card’s $0 annual fee.
Additional value may be available through Truist’s Loyalty Cash Bonus, which can add 10% to 50% to cash back redemptions when rewards are deposited into an eligible Truist personal deposit account, depending on the customer’s banking relationship. The card also includes contactless payments, mobile wallet compatibility, customizable card controls, and Visa Zero Liability protection for unauthorized purchases.
For readers considering whether the Truist Enjoy Cash Card fits their spending style, the next step may be to review how the application works, what documents may be required, and which rewards option could be the better match. Tap the button below to learn how to apply.
About Truist
Truist is one of the largest banking institutions in the United States and represents a modern blend of scale, traditional banking presence, and digital convenience. The brand was created in 2019 through the merger of BB&T and SunTrust, two long-established U.S. financial institutions. That merger gave Truist a significant national footprint and helped position it as a major player in consumer banking, lending, wealth services, and payments.
Although Truist supports a strong digital banking experience, it is not a digital-only bank. It is better described as a traditional bank with broad digital capabilities. Customers can use online banking and the Truist Mobile Banking App to manage credit cards, monitor transactions, redeem rewards, and use account security controls, while still having access to branches, ATMs, and phone support. This combination may appeal to people who want both in-person support and app-based convenience.
Beyond credit cards, Truist offers a wide menu of financial products and services, including:
- Personal checking and savings accounts
- Certificates of deposit
- Mortgages and home equity products
- Personal loans and lines of credit
- Small business banking
- Commercial banking
- Wealth management and investment services
- Insurance and payment solutions
As an issuer, Truist also highlights support tools such as fraud monitoring, card controls, contactless payments, and mobile wallet compatibility. For cardholders who value a relationship-based bank, this broader ecosystem can be relevant because some card benefits become more attractive when paired with eligible Truist deposit accounts.
Why choose the Truist Enjoy Cash Card?
The Truist Enjoy Cash Card is best suited to consumers who want a cash back credit card with no annual fee and who prefer either everyday simplicity or a more category-focused rewards setup. A major distinguishing feature is the ability to choose between two rewards options at application. One version offers 1.5% cash back on all eligible purchases, while the other offers 3% on gas and EV charging, 2% on groceries and utilities, and 1% on other eligible purchases, subject to a combined $1,000 monthly cap on the higher bonus categories. Because that choice cannot be changed later, the card can feel more personalized from the start.
This product may be especially relevant for people who want to keep their credit card strategy simple. The flat-rate version can work well for consumers who do not want to track categories. Meanwhile, the 3%-2%-1% version may fit households that spend regularly on fuel, groceries, utilities, or EV charging. In that sense, the card is not mainly designed for luxury travel users or premium card seekers. It is more of an everyday-use rewards card for practical spending.
Another strong reason to consider it is the 0% introductory APR for 12 months on purchases and 0% introductory APR for 12 months on balance transfers made within the first 90 days. For someone planning a major purchase or looking to consolidate existing card debt, this can add meaningful short-term value. The absence of an annual fee also lowers the barrier to entry, making it easier to keep the card long term without ongoing cost pressure.
There is also extra appeal for existing Truist banking customers. When rewards are redeemed through an electronic deposit into an eligible Truist personal deposit account, cardholders may receive a Loyalty Cash Bonus of 10% to 50%, depending on their qualifying relationship. That feature can materially improve the effective value of rewards for customers who already bank with Truist or plan to do so.
Overall, the Truist Enjoy Cash Card appears most appropriate for applicants seeking a mainstream U.S. cash back card, with relationship benefits, solid introductory financing, and the support of a large established bank. It may be particularly attractive to those who want rewards flexibility without moving into premium-fee territory.